
 Individual


- Home>
- Blog>
- Investments>
- One-Time Investment Plans



Invest ₹15K/Month & get ₹4.04Cr^1d Now!
If a lump-sum amount is investe...Read More


Trust of 20+ Years in Industry
Written bySumit Narula

Reviewed byKumar Himanshu
Last Modified 2nd November 2026
Investment Expert

What Is a One-Time Investment Plan?
One time investment plans can be defined as a financial product that require only a single lump sum investment to be made. Once invested, your money will grow over time through by accruing market-linked returns or interest. In the case, such investments, staying invested longer without withdrawing is recommended to maximising the benefit of compounding.
The choice of instrument for such a one-time investment can range from market-linked investments such as stocks, ULIP plans and mutual funds to fixed-return instruments such as fixed deposits and immediate annuity plans. Sources for funding a lumpsum required for such one-time investment plans can include annual bonus, savings, maturity amount from FDs, etc.
One Time Investment Plan Calculator
One time investment plan calculator also known as the lump sum investment calculator, is a simple online financial tool that you can use to plan your finances better. This investment calculator is designed to help you estimate the growth of your one-time investment over time.
In order to help you estimate your returns and the maturity value of your investments, below are the key inputs you are required to provide:
- Lump sum/One-time Investment (Principal Amount): This is the one time investment you are planning to make
- Expected Rate of Return: This is an estimate of the returns your expect from the investment plan
- Investment Period: This is the period for which you are staying invested in the plan Based on the above mentioned inputs, the one-time investment calculator will provide the below outputs: ul class="pl-5 mb-4 space-y-2 text-base list-disc text-primary">
- Maturity Value of the Investment- This is the size of the corpus at the end of the investment period
- Total Growth – This is the return that you have received from your investment
Additionally, you can also view of the chart/table of your investment overtime. This tool provides instantaneously results and there is no risk of miscalculation. This helps you plan your future investments better.
How Does a One-Time Investment Work?
This investment plan is simple but impactful in growing your investments if used properly. Below are key aspects about how one time investment plans work:
Step 1. Create a Investment Corpus
The first thing required to start a one-time investment plan is the creation of a corpus to invest. To maximise the benefits of a one-time investment, the initial investment required is relatively large. The source of a sufficiently large investment principal may be annual bonus, maturity payout of a FD/RD, existing savings, gratuity payouts, etc.
Step 2: Choose A Suitable Investment
Consider your financial goals and risk tolerance level. One-time investment plans are ideal if your are chasing a long-term goal that are 5 years or longer into the future. For instance, if you are seeking a low risk option, a long-term FD might be more suitable. Whereas, if you are looking to maximise returns, equity mutual funds might be a better option.
Step 3: Make the Investment
Making a lump sum one-time payment into your chosen plan is mandatory. While timing might not be required in case of fixed return investments, it is essential if you are investing in a market-linked instrument. Ideally, when making a one-time investment in a market-linked plan, you should time your investment when the market is low. This can help you maximise the potential benefits from your investment.
Step 4: Stay Invested for the Long Term
One time investment plans are ideally suited as long-term investments. With time, your investment will grow as interest from previous cycles earn more interest with time in the case of fixed-return instruments. In the case of market-linked instruments, market gains add up over time ensuring that your investments multiply over time. However, if you make premature withdrawals, it will impact the potential growth of your wealth. So, have patience and stay invested through changing market conditions.
One-Time Investment vs SIP: Key Differences to Consider
Although the primary goal of both SIPs and one-time investment plans is to build wealth, they differ in terms of their investment approach, market exposure, and the level of financial discipline involved. While SIPs involve investing small amounts of money regularly, one-time investments involve investing a single large amount all at once. Investors can take advantage of this information to choose an investment approach that matches their capacity, finnacial objectives, and investment horizon.
Investment Amount and Frequency
A systematic investment plan (SIP) requires you to make multiple investments of a fixed value at specified intervals, such as ₹10,000 per month for 12 months. While a lump-sum investment involves a larger investment amount like ₹1 lakh or ₹5 lakh that needs to be invested all at once. SIP often suits individuals with consistent monthly income such as salaried investors. On the other hand, lump-sum investment usually suits investors who have income fluctuation, either sue to seasonality of businesses profits or sudden windfall gains from property sale, inheritance, etc.
For example, a ₹10,000 monthly SIP invests ₹1.2 lakh over 12 months i.e. 12 separate transactions, whereas a ₹1.2 lakh lump sum is invested via a single transaction.
For example, a ₹10,000 monthly SIP invests ₹1.2 lakh over 12 months i.e. 12 separate transactions, whereas a ₹1.2 lakh lump sum is invested via a single transaction.
Market Exposure in One-Time Investment and SIP
With a one-time investment, the entire sum is exposed to the market from the moment of investment that’s, the entry point and market timing can become more crucial. SIP works by spreading investments across different market levels, called rupee cost averaging. For example, a ₹10,000 SIP purchases more units when the Net Asset Value (NAV) falls and fewer when the NAV of units is higher.
Flexibility and Investment Discipline
One of the key benefits of SIP allows for regular investment and can be a great way to cultivating investment discipline. Moreover this investment strategy allows you to invest in various instruments without having to come up with a significant corpus at once. A one-time investment lets you deploy surplus funds at once, but the entire sum will have exposure to same market condition, which can be good or bad depending on your ability to time the market. SIP also enables investors to keep investing through various market conditions including corrections and boom cycles.
Which Approach May Suit Your Financial Situation?
SIPs often suit the financial situation of salaried individuals, beginners, and those saving for long-term goals like retirement or education. One-time investment may suit investors who have a sizable surplus amount, a long investment period and tolerance to short-term market fluctuations.
An investment horizon of over 5 years is usually considered when comparing SIP and one-time investment approaches. Overall, the right choice depends on available capital, cash flow, risk tolerance, financial goals, and investment duration rather than on any fixed rule of thumb.
An investment horizon of over 5 years is usually considered when comparing SIP and one-time investment approaches. Overall, the right choice depends on available capital, cash flow, risk tolerance, financial goals, and investment duration rather than on any fixed rule of thumb.
Which is the Best Investment Plan in India for a One-Time Investment?
When you have a lump sum amount ready to invest, the real question is, where should you put it? In India, there is a series of one-time investment choices. Each option comes with its own range of features, benefits, risk profile, tax implications, and suitability as per your financial choices. Therefore, understanding these differences becomes necessary. This can help you assess how your one-time investment could grow.
Best Investment Plan with High Returns for 1 Year
If your investment horizon is around one year, saving your capital while earning better returns than a regular savings account should be your foremost priority. For short-term investments, you can consider fixed deposits, debt mutual funds, yield savings accounts, and liquid funds. Such options can lower your risk as compared to equity-based investments. Further, they offer stable returns.
While the return potential might not be very high, they offer better liquidity and have lower market volatility compared to market-linked investment options. Picking the right option depends on your liquidity needs and tax considerations, as well as on whether you prefer guaranteed or market-linked returns.
While the return potential might not be very high, they offer better liquidity and have lower market volatility compared to market-linked investment options. Picking the right option depends on your liquidity needs and tax considerations, as well as on whether you prefer guaranteed or market-linked returns.
Best Investment Plan for 5 Years with High Returns
Finding the best investment plan for 5 years with high returns depends on your individual goals and risk appetite. You need to pick an investment plan that is suited for your financial requirements. You can invest in a good plan for 5 years through a bank, insurance provider, or mutual fund company. It is wise to prefer a plan based on your risk appetite and investment goals.
Hybrid funds, National Savings Certificates, and market-linked insurance solutions can be suitable choices depending on your financial objectives. If you can accept moderate market risk, you might benefit from the long-term growth potential of equity-oriented investments.
Those looking for a balance between stability and returns can go for hybrid options. Before investing, make sure to compare your expected returns, tax benefits, lock-in periods, and investment flexibility. This is how you can select a plan that matches your goals.
Hybrid funds, National Savings Certificates, and market-linked insurance solutions can be suitable choices depending on your financial objectives. If you can accept moderate market risk, you might benefit from the long-term growth potential of equity-oriented investments.
Those looking for a balance between stability and returns can go for hybrid options. Before investing, make sure to compare your expected returns, tax benefits, lock-in periods, and investment flexibility. This is how you can select a plan that matches your goals.
Long-Term Investment Plans for Wealth Creation
A Unit-linked Insurance Plan is one of the best long-term investment plans that offers the dual benefit of long-term goal-fulfilling investment and life insurance protection. You can also consider stocks as a beneficial option, as they provide you with fractional ownership in a company.
This ownership comes with the potential for gains through increased stock price and dividends. The National Pension Scheme is also a desirable option that is backed by the government of India. It is considered to be a voluntary retirement savings scheme that allows you to save for your retirement.
You can invest between 10 and 65 years of age and continue investing till you are 75 years old. Further, NPS offers a tax deduction of up to ₹50,000 per annum. Staying invested over a longer period can help manage short-term market volatility and encourage wealth accumulation potential.
This ownership comes with the potential for gains through increased stock price and dividends. The National Pension Scheme is also a desirable option that is backed by the government of India. It is considered to be a voluntary retirement savings scheme that allows you to save for your retirement.
You can invest between 10 and 65 years of age and continue investing till you are 75 years old. Further, NPS offers a tax deduction of up to ₹50,000 per annum. Staying invested over a longer period can help manage short-term market volatility and encourage wealth accumulation potential.
Which Investment Scheme Matches Your Financial Goals?
The ideal investment scheme depends on what you want to get and when you need the money. For short-term goals, low-risk investment options with high liquidity might be more appropriate. Medium-term goals can be supported through balanced or hybrid investment solutions, while long-term objectives often benefit from equity-oriented investments.
If protecting your family's financial future is equally necessary, you can consider investment plans that combine wealth creation with life insurance benefits. Therefore, assess your income and financial commitments, along with your investment horizon, before making a decision. This ensures your one-time investment supports your overall financial goals.
If protecting your family's financial future is equally necessary, you can consider investment plans that combine wealth creation with life insurance benefits. Therefore, assess your income and financial commitments, along with your investment horizon, before making a decision. This ensures your one-time investment supports your overall financial goals.
Key Benefits of One-Time Investment Plans
Best one time investment plan with high return options helps to overcome inflation and accumulate wealth rapidly. These plans are highly beneficial.
Potential For High Returns
Investing a large amount in an investment plan at once can be lucrative as long as . This can potentially help your wealth grow faster so that you can reach your financial goals with relative ease.
Simplified Investment Process
Since one-time investment plans require a single relatively large investment, the process is relatively straightforward. Also, there is no need to track your payment schedules after making the investment. So, you do not need to worry about issues such as failed auto-debits, frequent portfolio rebalancing, etc.
Ideal for Long-Term Goals
Staying invested longer is essential in the case of one-time investment plans. This means the plan will be ideally placed to maximise the potential benefits of compounding. So, one-time investment plans are ideally placed to achieve long-term financial goals that are 5 years or more in the future. Examples of such goals may include creation of a retirement corpus, saving for children’s higher education or marriage, etc.
Wide Range of Investment Options
One-time investment plans in India currently allow access to a wide range of asset classes. Some offer the benefit of fixed returns that ensure low volatility and assured long-term returns. Others can offer inflation beating returns that is ideally suited for long-term wealth creation. The wide range of options available ensures that a suitable one-time investment plan can be found for every investor no matter how unique their financial requirements are.
Immediate Access to Returns
A one-time investment plan allows immediate access to the returns being offered. While the actual return may vary based on the specific plan chosen, your investment can potentially start giving returns almost as soon as you make your investment. However, do keep in mind that market-linked investments will be subject to volatility, especially in the short term. So ensure that you stay invested over the long term to maximise the potential benefits of financial planning using a one-time investment.
One-Time Investment Plans with High Return in India
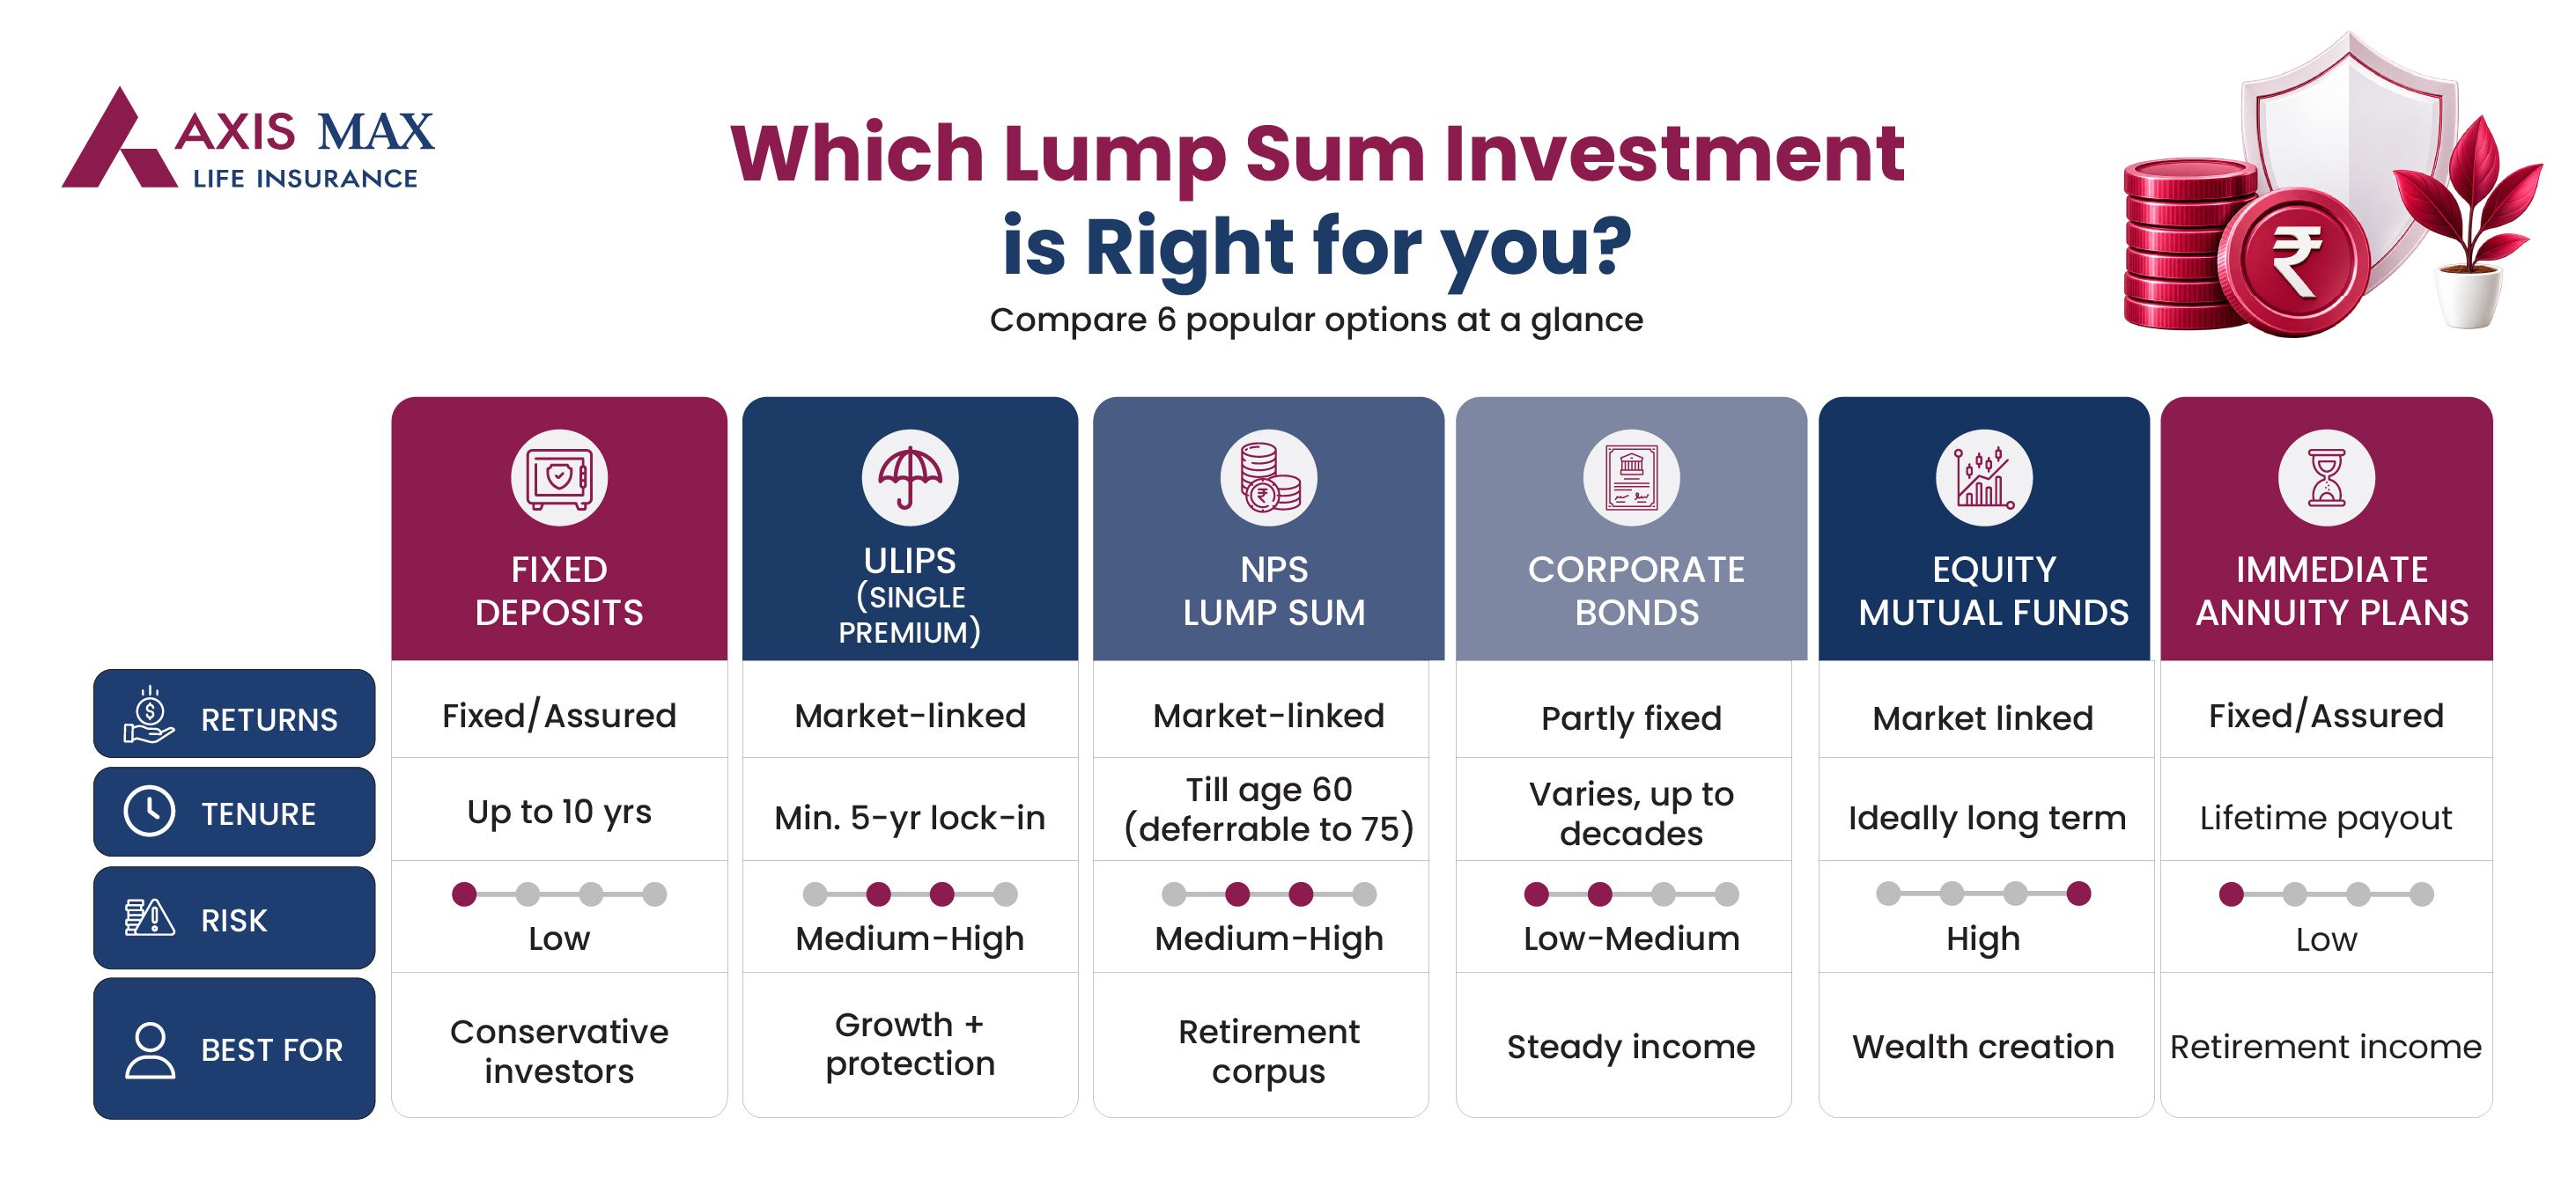
Each one-time investment plan offers different benefits and return potential. So no there is no single one that can be considered as the best one-time investment plan in India. The following chart will help you to know the different options currently available along with their key features so that you can choose a plan that is suited to your unique needs:
| Type of Plan | Returns | Time Period | Risk Level | Best For |
|---|---|---|---|---|
| Fixed Deposits (FDs) | Assured returns fixed at inception and unchanged till maturity | Up to 10 years | Low | Conservative Individuals seeking assured returns |
| Unit Linked Insurance Plans (ULIPs) - Single Premium | Market-linked and returns are not guaranteed | Minimum lock-in of 5 years | Medium to High | Individuals seeking dual benefit of Growth and protection |
| National Pension System (NPS) Lump Sum | Market-linked and returns are not guaranteed | Until subscriber reaches the age of 60 years but can be deferred till the age of 75 years | Medium to High | Individuals seeking to build a corpus for financial security in retirement |
| Corporate Bonds | Partially fixed returns based on coupon rate, but overall returns subject to bomd market movements | Maturity varies based on the bond and can be extend to decades | Low to Medium | Individuals with low to medium risk tolerance seeking steady income over the long-term |
| Equity Mutual Funds | Returns are not assured and linked to market performance | No maximum limit on investment duration | High | Investors with high risk tolerance seeking potentially high long-term capital appreciation |
| Immediate Annuity Plans | Returns are assured and pre-determined at inception | Can offer payout during the lifetime of the annuitant | Low | Individuals seeking regular income during their post-retirement years |
How to Maximise Returns from a One-Time Investment Plan?
A one-time investment plan is one of the most accessible investment options that offers diversification and substantial returns. To encourage the potential of your mutual fund investments, it is important to adopt specific strategies.
Following a disciplined approach, picking suitable investment options, and assessing your portfolio regularly can help you improve your return potential while keeping your investments tailored to your changing financial requirements.
1. Stay Invested for the Long Term
One of the essential ways to maximise your returns from a one-time investment plan is to stay invested for the long term. With time, investments have the opportunity to get the benefits of compounding, where the returns generated are reinvested and might generate additional returns. Investing long term also means that you are not affected by temporary market fluctuations, especially for equity mutual funds or ULIPs.
Therefore, instead of reacting to temporary market movements, staying invested with a long-term perspective helps your portfolio recover from volatility and achieve potential growth over multiple market cycles.
Before you invest, make sure to select an investment plan that matches your financial timeline and avoid withdrawing funds unless it is crucial. Consistency often plays a major role in helping investors build wealth and achieve long-term financial objectives with no drawbacks.
Therefore, instead of reacting to temporary market movements, staying invested with a long-term perspective helps your portfolio recover from volatility and achieve potential growth over multiple market cycles.
Before you invest, make sure to select an investment plan that matches your financial timeline and avoid withdrawing funds unless it is crucial. Consistency often plays a major role in helping investors build wealth and achieve long-term financial objectives with no drawbacks.
2. Diversify Across Investment Options
Diversification is a fundamental strategy to handle risk and encourage returns. By spreading your investments across multiple types of mutual funds, you can prevent the influence of poor performance from any fund. To diversify effectively, you need to invest in multiple types of investment options.
Consider a mix of equity, hybrid, and debt funds. Equity funds offer higher returns but come with higher risk. On the other hand, debt funds offer stability with lower returns. Allocate your investments across several sectors like healthcare, technology, and finance to eradicate sector-specific risks.
As different asset classes perform differently under multiple market conditions, diversification can help you reduce the overall influence of market volatility on your portfolio. It also offers better balance by ensuring that underperformance in one investment might be offset by stronger performance in another. The right asset allocation depends on factors like liquidity needs, investment horizon, and risk appetite.
Consider a mix of equity, hybrid, and debt funds. Equity funds offer higher returns but come with higher risk. On the other hand, debt funds offer stability with lower returns. Allocate your investments across several sectors like healthcare, technology, and finance to eradicate sector-specific risks.
As different asset classes perform differently under multiple market conditions, diversification can help you reduce the overall influence of market volatility on your portfolio. It also offers better balance by ensuring that underperformance in one investment might be offset by stronger performance in another. The right asset allocation depends on factors like liquidity needs, investment horizon, and risk appetite.
3. Review Your Portfolio Periodically
Assessing your investments is necessary to ensure they continue to align with your goals. Periodic assessment and rebalancing can help you maintain your desired asset allocation. Make sure to review your portfolio at least annually or semi-annually.
If one part of your portfolio grows significantly more than others, rebalance by selling some of the outperforming assets and buying more of the underperforming ones to maintain your original allocation. It ensures that your investments continue to support your financial objectives and remain suitable for your current situation.
Reviewing your portfolio allows you to assess whether your asset allocation has shifted significantly and whether rebalancing is important. It also offers you an opportunity to evaluate the performance of multiple investments and identify underperforming assets. This can help keep your investment strategy consistent with your long-term financial plan and encourages the overall effectiveness of your portfolio.
If one part of your portfolio grows significantly more than others, rebalance by selling some of the outperforming assets and buying more of the underperforming ones to maintain your original allocation. It ensures that your investments continue to support your financial objectives and remain suitable for your current situation.
Reviewing your portfolio allows you to assess whether your asset allocation has shifted significantly and whether rebalancing is important. It also offers you an opportunity to evaluate the performance of multiple investments and identify underperforming assets. This can help keep your investment strategy consistent with your long-term financial plan and encourages the overall effectiveness of your portfolio.
4. Align Investments with Financial Goals
Every investment should have a proper and clear goal. Before you pick a one-time investment plan, identify the financial goal you want to achieve, whether it is buying a home, funding your child’s education, planning for retirement, or building long-term wealth. Your investment horizon, expected returns, and risk appetite should reflect all your objectives.
For example, short-term goals might be better served through stable investment options, while long-term goals can benefit from investments with higher growth potential despite short-term market fluctuations. It is also necessary to consider factors like liquidity needs, insurance requirements, and tax implications while selecting an investment plan.
When your investments are directly linked to specific financial goals, it becomes easier to stay disciplined and monitor progress.
For example, short-term goals might be better served through stable investment options, while long-term goals can benefit from investments with higher growth potential despite short-term market fluctuations. It is also necessary to consider factors like liquidity needs, insurance requirements, and tax implications while selecting an investment plan.
When your investments are directly linked to specific financial goals, it becomes easier to stay disciplined and monitor progress.
One Time Investment Plan with Tax Benefit
Some one-time investment plans allow you to avail tax benefits. However, as per current rules, these tax benefit from investments are only available if you have opted for the old tax regime. Below are examples of one time investment plans in India that offer tax benefits:
| Investment Plan Name | Tax Benefit Offered |
|---|---|
| Fixed Deposits (FDs) | Tax saver 5 year FD offers tax benefit u/s 80C at the time of investment |
| Unit Linked Insurance Plans (ULIPs) |
|
| National Pension System (NPS) | Tax benefit up to ₹2 lakh annually u/s Section 80 CCC, Section 80 CCD(1) and Section 80 CCD(1B) |
| Corporate Bonds | Interest earned from tax-free bonds are tax exempt under Section 10(15)(iv)(h) |
| Equity Mutual Funds | Tax benefit u/s Section 80C are applicable only in the case of equity-linked savings schemes (ELSS) |
| Immediate Annuity Plans | Benefit under Section 80C up to the applicable limit of ₹1.5 lakh |
Choose the Right Investment Option
The choice of investment plays a crucial role in determining how long you will need to stay invested in order to avail the benefits offered under the plan. Additionally, the level of risk applicable to an investment also varies.
For instance, if you are planning to stay invested for a period of 5 years or longer, an equity-oriented investment might be a good fit to help you maximise the potential benefit from the investment. On the other hand, a one-time investment in a fixed return investment such as fixed deposit or annuity plans may be more suitable, if you have low risk tolerance and are seeking assured returns.
For instance, if you are planning to stay invested for a period of 5 years or longer, an equity-oriented investment might be a good fit to help you maximise the potential benefit from the investment. On the other hand, a one-time investment in a fixed return investment such as fixed deposit or annuity plans may be more suitable, if you have low risk tolerance and are seeking assured returns.
Put Surplus Funds to Productive Use
These investment plans are an excellent option of you have surplus funds handy and are looking to put them to use. Making these investments allows you to maximise the potential benefit you can receive from surplus cash that you might have available. This allows you to make your money work for you instead of leaving it idle in a savings bank account to earn a minimal amount of interest.
Check the Credibility of the Provider
One time investment plans are offered by a wide range of providers ranging from public and private sector banks to life insurance companies. If you invest with a reputable and credible provider, you can look forward to high degree of transparency that minimises the risk of fraud and financial risk. A credible provider will also ensure that you receive clear communication so that you are aware of potential risks, benefits as well as tax and other regulations that may impact your investments.
Investors with Medium to Long-Term Financial Goals
Investors who are seeking to achieve financial goals that are 3 years or further in the future can opt for various one-time investment plans based on their unique needs. In case of goals that are to be achieved in the medium term, a one-time investment in a plan that offers fixed returns might be suitable. Such plan can provide an ideal balance between risk and return.
Similarly, if your financial goals are further in the future such as retirement, saving for your child’s education, etc. they are considered as long term goals. For such long term goals, investments plans that have the potential of delivering inflation-beating long term returns are preferable. In such a situation, one-time investment is equity-focused investment plans may be preferable.
Similarly, if your financial goals are further in the future such as retirement, saving for your child’s education, etc. they are considered as long term goals. For such long term goals, investments plans that have the potential of delivering inflation-beating long term returns are preferable. In such a situation, one-time investment is equity-focused investment plans may be preferable.
People Looking for Tax-Saving Investment Options
Those seeking tax-saving investment options may choose to opt for various one-time investment plans. The tax benefits of one-time investment plans may be available either as a the time of making the investment or at the time of maturity.
Examples of one-time investment plans that can offer tax benefits to individuals include – tax saving at the time of making the investment and tax exemption benefit on returns. For instance, pension plans such as an immediate annuity plan and tax saving fixed deposit offer tax deduction benefit at the time of making investment. On the other hand, interest payouts from tax free bonds are tax exempt in India as per rules of Section 10(15)(iv)(h) of the Income Tax Act.
Examples of one-time investment plans that can offer tax benefits to individuals include – tax saving at the time of making the investment and tax exemption benefit on returns. For instance, pension plans such as an immediate annuity plan and tax saving fixed deposit offer tax deduction benefit at the time of making investment. On the other hand, interest payouts from tax free bonds are tax exempt in India as per rules of Section 10(15)(iv)(h) of the Income Tax Act.
Tax Benefits of One-Time Investments in India in 2026
Different investment options are governed by different tax rules, and the taxes applicable on maturity can make a difference in the overall returns received from a one-time investment plan. With a one-time investment in India in 2026, here are the most crucial tax considerations and benefits to keep in mind.
Taxation of Fixed-Income One-Time Investments
Investments in fixed-income securities like fixed deposits (FDs), Public Provident Fund (PPF) and National Savings Certificates (NSC) fall under different tax provisions. The interest earned on regular Fixed Deposits, NSC and tax-saving FDs are taxable irrespective of the tax regime chosen. This has to be factored in when considering net returns from your investment plan. PPF offers tax benefits on the contributions, interest, and maturity proceeds it is a exempt-exempt-exempt (EEE) instrument.
●Taxation of Mutual Funds and Other Market-Linked Investments
Taxation of market-linked investments differs depending on the type of investment, period of holding the investment and the tax rules. Equity-oriented mutual funds have a tax rate of 20% on total gains without indexation benefit for short-term capital gains i.e. holding period of less than 1 year. In case of holding period exceeding 1 year, the long term capital gains tax is 12.5% on equity gains exceeding ₹1.25 lakh in a tax year without indexation benefit.
Debt mutual funds returns are taxed at the income tax slab rate irrespective of their holding period. On the other hand, the tax liability on balanced advantage funds depends on whether they are classified as equity funds or non-equity funds.
Tax Benefits on One-Time Investment Options
There are several investment options that provide tax benefits if they are chosen based on financial objectives and qualification. PPF can be deducted under Section 80C, while investments in tax-saving FDs, NSC, and ELSS mutual funds may be eligible for deduction under Section 123 read with Schedule XV, with a limit of ₹1.5 lakh under the old tax regime.
NPS contributions are allowable as a deduction under Section 124, subject to the applicable tax regime and meeting the eligibility criteria. Conditions apply to tax exemptions on life insurance policies and other eligible instruments as per the Income Tax Act, 2025.
NPS contributions are allowable as a deduction under Section 124, subject to the applicable tax regime and meeting the eligibility criteria. Conditions apply to tax exemptions on life insurance policies and other eligible instruments as per the Income Tax Act, 2025.
Tax Considerations Before Making a One-Time Investment
Prior to making a lump sum investment, compare the after-tax returns, lock-in period, liquidity and risk of the investment. Check whether the investment gives any tax deduction in the selected tax regime, as most tax deductions under Section 123 are not available under the new tax regime.
Take into account the tax implications on interest, dividends and capital gains, as well as investment objectives and time horizon. Investing solely for the tax advantage may not be the aligned with the investment benefit that you seek.
Take into account the tax implications on interest, dividends and capital gains, as well as investment objectives and time horizon. Investing solely for the tax advantage may not be the aligned with the investment benefit that you seek.
How to Invest in One-Time Investment Plans?
One-time investment plans have now become more affordable with online as well as offline investment options offered to investors. The procedure could differ depending on the kind of investment you opted for. However, the majority of the options require a simple application and validation process.
1. Online vs Offline Investment
Online and offline investment modes have varying benefits with respect to convenience, accessibility, and preference for financial advice to an investor.
2. Online Investment
- Select an Investment Plan: Select an appropriate investment plan using the bank's website, investment platform, insurance platform, mobile applications, or brokerage account.
- Complete Application and KYC Verification: Fill out an application and KYC verification online.
- Make the Payment Online: The lump sum payment is made online using linked banking options.
- Monitor and Manage Investments: Monitor and manage investments without any difficulties via online dashboards and mobile apps.
3. Offline Investment
- Visit a Financial Institution: Go to a bank branch, financial institution, insurance office, or an approved financial advisor.
- Choose a Suitable Investment Plan: Choose an appropriate one-time investment plan depending on your financial objectives and risk profile.
- Complete the Application Process: Physically fill out the investment application and deliver the necessary documents.
- Make the Payment: Pay by cheque, cash, or bank transfer as accepted by the provider.
4. Documents Required
Investors will have to undergo a KYC verification and provide some standard documents before investing in a one-time investment plan.
- PAN Card for Identity Verification: PAN card to verify identity and pay taxes.
- Address Proof Documents: Aadhaar card, passport, voter ID, or utility bills as address proofs.
- Application Records: Application records (passport-sized photographs).
- Bank Account Information: Bank account information like cancelled cheque or a bank statement, to make a payment.
- Income Proof for High-Value Investments: Some high-value investment products might need income evidence.
- Age Proof and Nominee Details: Age proof and nominee details might be required in ULIPs, annuity plans, or investments aimed for retirement.
Why Should You Choose the Axis Max Life One-Time Investment Plan?
One-time investment plans offered by Axis Max Life Insurance can provide a range of benefits. Policyholder opting for such plans can expect to avail key benefits such as:
Professional management
Your hard-earned money is managed by professional fund managers. Their experience and expertise can help long-term growth of your investments. So, your wealth creation with require minimal effort on your part after you have made the investment.
Unmatched Custimisation
One-time investment plans from Axis Max Life offer excellent potential for long-term growth or regular lifetime income through a wide range of investment options. Depending on your unique needs, you can opt for actively managed or passively managed funds or spread your investments across equities, debt or hybrid funds.
Life Cover
All Axis Max Life Insurance one-time investment plans feature in-life cover benefit. This ensures that the policyholder’s loved ones have access to a financial safety net even if the policyholder is no longer around.
Tax Benefits
One-time investment plans from Axis Max Life offer various tax benefits. The lumpsum investment made into the plan is eligible for tax benefits under Section 80C, if the policyholder files returns under the old tax regime. The maturity payout from these plans are also exempt from tax as per current rules under Section 10 (10D) irrespective of the tax regime chosen.
Key Factors Influencing One-Time Investment Decisions
There are a variety of factors that can impact decisions regarding which one-time investment plan is ideally suited to an individual’s financial needs. Below mentioned are some of the key factors to consider:
- Market conditions: Consider the current market situation before investing any lump sum in a market-linked one-time investment plan. Monitor key financial ratios such as Price-to-Earnings (P/E) ratio of broad-based market indices, like the Nifty 50 and the Sensex Indices. As per historical data, a P/E ratio close to 14 means the market is potentially undervalued and more likely to offer high returns in the long term.
- Return potential: Gauge the historical performance of the funds that you are considering and gauge their expected returns. You can easily decide whether the potential returns align with your financial goals. In case you have low risk tolerance, it mght be more prudent to opt for a relatively low risk one-time investment plan that can offer assured returns.
- Liquidity needs: Know your current financial situation and future need for funds in an emergency. Make sure that you can have quick access to cash in case of any emergencies before you make a one-time investment. This will make sure you do not have to make premature withdrawals that can adversly impact long-term growth of your investments.
- Ability to stay invested: Investing typically pays off if you are patient and stay invested in the long-term over various market conditions. So, do not panic or redeem your investments prematurely when markets are volatile. The chances of getting better returns through the benefit of compounding will be higher if one stays invested for a longer time period.
Who Needs a One Time Investment?
If you have surplus money today and a long-term financial goal, a one-time investment is an effective option. Typically, investing for the long-term offers more benefit to the investor instead of maintaining a large bank balance that earns minimal returns. Below are some key groups of individuals who may benefit by opting for one-time investment plans:
- Salaried Individuals: They might receive annual bonuses, incentive payouts, or gratuity payouts. These are often relatively large sums of money that can be invested in one-time investment plans to earn potentially high long-term returns.
- Retirees: These individuals might have substatial savings that are not producing much returns. One-time investment plans such as immediate annuity plans can provide a potentially lower-risk investment route that provides a steady income in old age.
- Inheritance/Windfall Recipients: People who have suddenly received a large sum of money, like an inheritance or lottery win, and want to invest it smartly. A one-time investment
- Parents: For their children's education or future milestones, investing a lump sum instead of monthly premiums.
- Long-Term Planners: Anyone with a significant time limit (like young professionals) for goals such as retirement or buying a house.
- Investors Seeking Simplicity: Those who prefer a hands-off approach and do not want to manage recurring payments.
Risks Associated with Lump Sum Investments
While lump sum investments can have good long-term return potential, they also have some financial risks. You should consider these risks before investing a large sum at once:
1. Market Timing Risk
Market entry at an inappropriate time is one of the greatest risks of lump sum investing. When the investment is made at market highs, short-term fluctuations or declines can have long-lasting impacts on the portfolio value. This especially applies to the market-related investments like mutual funds, ULIP, and equities.
2. Volatility Impact
Market fluctuations directly impact the performance of lump sum investments. The equity-based instruments can be subjected to a sudden change in price based on economic factors, interest rates, or world events. Such volatility can be a challenge to investors who have a lower risk appetite, particularly when markets are falling in the short term.
3. Liquidity Constraints
Some of the one-time investment plans are associated with lock-in or restricted withdrawal provisions. PPF, NPS, ULIPs, and real estate investments may limit easy access to the funds, which can be hard at the time of a financial crisis or unexpected liquidity constraint.
4. Inflation Risk
There are low-risk investment choices that might not pay returns that keep up with inflation in the long run. Even though investments like fixed deposits and traditional savings tools may offer a guaranteed return over a certain period, their purchasing power could eventually depreciate due to inflation.
How to Manage Market Timing Risk in a One-Time Investment?
Market timing risk can affect the returns of a lump sum investment plan, especially when a large amount is invested during periods of market boom. The following are key ways to manage this risk and make informed investment decisions.
Understand Your Investment Horizon
Having a longer investment time frame provides a longer window for the market to recover from short-term swings and more time for compounding to grow your investment. Match the time horizon of investment to financial objectives, such as retirement, education, and wealth building.
Avoid Making Decisions Based Only on Short-Term Market Movements
Short-term market fluctuations can lead to impulsive decision-making that can have undesirable long-term consequences. Rather than focusing on short-term price fluctuations, focus on investment objectives, risk tolerance, and market fundamentals when choosing your investments.
Consider Phased Deployment for a Large Corpus
Large corpus investments can be made in stages instead of a single investment to ensure the entry dates are evenly distributed throughout the market and avoid excessive exposure to the entry price. This approach can reduce the timing risk, but doesn't guarantee higher returns compared to investing the entire amount all at once.
Review Risk Before Investing
Before investing a lump sum, take your risk appetite, financial goals and equity, debt or hybrid fund option into account. Choose investments which are compatible with your capacity to withstand market volatility and the time available to reach your stated financial objectives.
How to Choose the Right One-Time Investment Plan?
The parameters that you should consider while selecting the right plan are,
- Financial Goals: What are you saving for (retirement, home, education)? Your goals will be the deciding factor for the kind of plan that suits you.
- Risk Tolerance: How comfortable are you dealing with market fluctuations? Higher risk generally means the possibility of higher returns (e. g., Equities). Low risk offers greater stability (e.g., Fixed Deposits).
- Investment Period: How long can you keep the money invested? For long-term goals, you can select growth-focused assets such as equities. While for shorter investment periods, hybrid, debt or fixed-returns investments may be preferable.
- Market Conditions: Study the economic trend. If the market is undertow (like low P/E ratios), then it may be a good time for long-term investing in stocks. However, a high-volatility market is more suitable for debt.
- Asset Allocation: Decide on the combination of equities (stocks), debt (bonds/FDs), or hybrid funds. Diversifying investments across multiple asset classes can help optimise returns and reduce overall investment risk.
- Liquidity: How quickly can you get your hands on the money? Some of the investments might have a lock-in period. Consider the potential liquidity requirements before making your choice.
- Costs & Fees:Learn about management fees, entry/exit loads, and how they affect the net returns. Higher fees and charges can potentially reduce the overall returns you might expect from your investment.
- Tax Implications: Think about potential tax benefits of the one-time investment plan. Additionally one also needs to consider the possible impact of capital gains taxation rules.
Conclusion
One-time investment plans can support wealth creation, regular income, and long-term financial goals through lump sum investments. You can choose from low-risk options like Fixed Deposits to higher-risk products like Mutual Funds and ULIPs based on your financial objectives and risk appetite. Selecting the right one time investment plan as a high-return option depends on returns, liquidity, taxation, and risk to support long-term financial stability.
FAQs on One-Time Investment Plans

What are the different types of one-time investment plan?
Currently one-time investments plans can be made through various instruments such as fixed deposits, mutual funds, ULIPs, bonds, etc. Your choice should match your risk tolerance and unique financial objectives.
Which is the best one-time investment plan with high returns?
Not all one-time investment plans offer assured returns, so no single plans can be considered as best based on its current or potential returns. While options such as fixed deposits can offer assured returns, market-linked options have the potential of offering higher long-term returns. But in case of market-linked instruments returns are not guaranteed.
Is it better to make a one-time investment or go for a SIP?
A one-time investment is suitable for a large sum of money. If you want to invest relatively smaller amounts each month, a systematic investment plan might be more suitable. Additionally, one-time investment plans require you to time markets to maximise potential benefits. But this is not necessary with SIP due to rupee cost averaging.
How much should I put in a one-time plan?
Many one-time investment plans have a minimum investment amount criteria that you need to meet. Higher amounts can be invested in most cases, based on how much money you have available, your financial goals and your risk appetite.
Do one-time investments qualify for tax benefits?
Yes, some one-time investment plans offer tax deduction benefit on investments made. Examples of such plans include ULIPs, tax saver FD and ELSS tax saver mutual funds which offer tax deduction under Section 80C. However, only investors who opt for the old tax regime can avail these benefits.
It is possible to withdraw my one-time investment before maturity?
Yes, many one-time investment plans provide the option of making withdrawals before maturity. However, If you decide to withdraw early, you may have to pay a penalty for premature withdrawal or receive lower returns over the long term.
What are the risks of one-time investment plans?
The risk depends on the type of plan. Equity-linked investments and ULIP plans may carry significant market risk. On the other hand, fixed deposits and debt funds are relatively low risk investments but may be unable to provide inflation-beating returns in the long term.
Can I get monthly income from a one-time investment plan?
Yes some one-time investment plans such as fixed deposits with monthly interest payouts and immediate annuity plans offer the benefit of monthly income. These are often preferred by retired individuals and others who want assured and regular income.
How does a one-time investment plan calculator work?
A one-time investment plan calculator is a free online financial tool that can help you plan your investments with greater confidence. This calculator requires 3 key inputs to operate – Principal Amount Invested, expected rate of return and time period of investment.
Based on the these inputs, the calculator provides the corpus created at maturity and the total returns received from the investment.
Based on the these inputs, the calculator provides the corpus created at maturity and the total returns received from the investment.
Can I split a lump-sum investment across multiple investment options?
Yes, you can split a large one-time investment across various investment options such as stocks, bonds, and mutual funds to help you build a diversified portfolio that aligns your risk profile. This type of strategic asset allocation can help minimise the risk of market timing and volatility by diversifying across asset classes and sectors, which helps promote long-term return potential.
Can NRIs make one-time investments in India?
Yes, Non-Resident Indians (NRIs) are allowed to invest in India via lump-sum amount in assets such as mutual funds, stocks, or property. These investments have to be made through special bank accounts denominated in rupees, such as an NRE Bank account for eligible investments to be repatriated or an NRO Bank account where investments are subject to applicable repatriation restrictions, subject to FEMA regulations and KYC requirements.
Can I make another lump-sum investment after my first investment?
Yes, you can make multiple lump-sum investments at any time after you invested your initial sum, if the investment plan permits additional investments. Most mutual funds, brokerage accounts and flexible investment plans allow for multiple lump-sum purchases, with certain accounts, like retirement accounts, having minimum purchase amounts and maximum annual limits.
How should I invest an inheritance or windfall gain?
To invest a windfall gain or inheritance received in India efficiently, prioritise clearing high-interest debts, building a 6-to-12-month emergency fund and allocating the remainder into a diversified portfolio of Equity Mutual Funds (via STP) and PPF/EPF for long-term growth. Ensure tax optimisation by utilising capital gains exemptions benefits, if the windfall is from property sale. It is also recommended that you consult a SEBI-registered investment advisor for guidance regarding how you can align the corpus with your specific financial goals.
How can I manage market timing risk when making a one-time investment?
For a lump-sum investments made in India, a systematic transfer plan (STP) can be used to invest in a liquid mutual fund and systematically transfer portions of the invested corpus into an equity mutual fund within a period of 6 months to 12 months. This method helps in rupee cost averaging because it enables investors to buy more shares at low prices and fewer shares at high prices, thus eliminating the need to time markets at the time of investing.
ARN: Feb26/Bg/10F
Sources:https://www.gripinvest.in/blog/one-time-investment-plans
https://www.bajajfinserv.in/investments/nps-interest-rates
https://www.fincart.com/blog/equity-sip-investments/
https://www.bajajfinserv.in/investments/nps-interest-rates
https://www.fincart.com/blog/equity-sip-investments/
Share your Valuable Feedback

4.2
Rated by 612 customers
Was the Information Helpful?
Very Good
Popular Searches
Online Sales Helpline
- Whatsapp: +91-7428396005Send ‘Quick Help’ from your registered mobile number
- Phone: +91-124-648-890009:30 AM to 06:30 PM
(Monday to Sunday except National Holidays) - service.helpdesk@axismaxlife.comPlease write to us incase of any escalation/feedback/queries.
Customer Service
- Whatsapp: +91-7428396005Send ‘Hi’ from your registered mobile number
- 1860-120-55779:00 AM to 6:00 PM
(Monday to Saturday) - service.helpdesk@axismaxlife.comPlease write to us incase of any escalation/feedback/queries.
NRI Helpdesk
- +91-11-71025900 , +91-11-61329950 (Available 24X7 Monday to Sunday)
- nri.helpdesk@axismaxlife.comPlease write to us incase of any escalation/feedback/queries.